Diplomacy moves faster than industrial capacity
The expected meeting between Donald Trump and Xi Jinping this week brings a persistent asymmetry into focus. Washington can change tariffs or announce financial support quickly, but replacing a specialised supply chain takes much longer. Reuters reported on 15 November that many US critical-mineral projects remain years from production despite federal investment. It also described a possible extension of the existing trade truce, due to expire in January, including waivers for certain mineral export controls. These are reported negotiating possibilities, not an agreement already reached. Access can be negotiated while the capacity needed to make that access less essential remains unfinished. [1]
The market question is therefore not whether a summit produces reassuring language. It is whether manufacturers gain reliable supplies while alternative production becomes commercially usable. A temporary accommodation can protect today's output without eliminating tomorrow's dependence. Conversely, a credible diversification programme can strengthen resilience before it replaces every import. Keeping those horizons separate helps explain why a diplomatic improvement need not invalidate the investment case for new processing capacity, and why a large investment announcement cannot by itself establish that industrial vulnerability has disappeared.
The concentration increases as the material moves downstream
Rare earths are a group of 17 elements, but the relevant supply chain here is narrower: the magnet materials neodymium, praseodymium, dysprosium and terbium. The IEA records China accounting for 60% of global mined production of magnet rare earths in 2024, 91% of refined output and 94% of permanent magnet production. These are historical production shares, not November 2026 market shares or interchangeable measures of installed capacity. Their progression reveals the central problem. Diversifying extraction alone leaves subsequent conversion stages heavily concentrated. A mine outside China does not necessarily supply a finished magnet outside China. [2]
The chain includes concentrating ore, chemical processing, separation into individual oxides, conversion into metals, alloying and magnet manufacturing. Each stage needs equipment, technical knowledge and consistent inputs. The magnets must then match a customer's specifications. A new deposit can increase available mineral resources without solving a shortage of separation capacity or qualified components. This distinction also limits the usefulness of broad critical-mineral labels: copper, lithium and rare-earth magnets serve different applications and require different processes. Progress in one cannot automatically be counted as an answer to a bottleneck in another. [2]
A small component can constrain a much larger production system
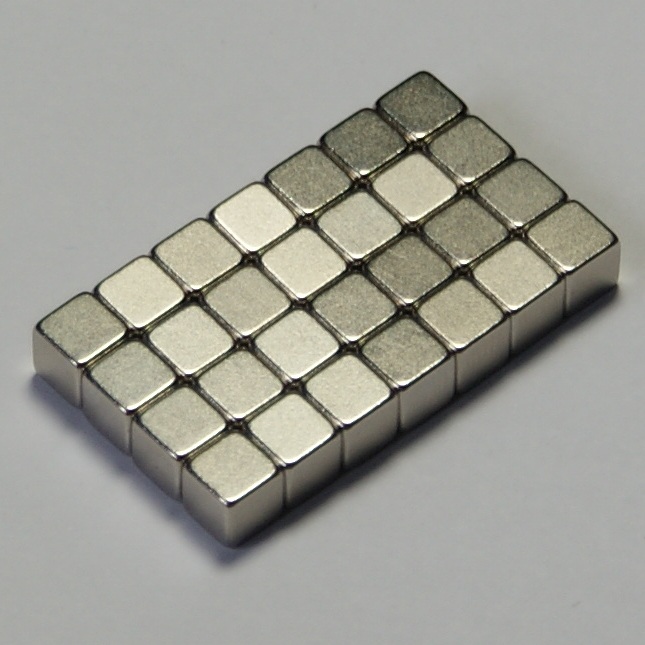
High-performance neodymium-iron-boron magnets support electric vehicles, wind turbines, industrial motors and other strategic applications. Their economic importance exceeds their weight or purchase price. If an essential component is unavailable, a manufacturer may be unable to complete a product whose other parts have already been bought. The IEA documents sharp export declines following China's April 2025 controls and production disruptions at some automakers before licences were granted and shipments recovered. Those disruptions are historical evidence of the transmission mechanism, not proof that the same shutdowns are occurring today. [2]
The first effect is often operational rather than visible in a broad commodity benchmark. Businesses may accumulate unfinished goods, pay for expedited transport or hold additional inventory. A supplier can retain demand but lose sales because its customer has slowed assembly. Working capital can deteriorate while orders remain healthy. This makes the value of secure delivery different from the value of the material itself. It also explains why tariffs and export licences are not equivalent instruments: a tariff changes the cost of a purchase, while a withheld authorisation can prevent the purchase from reaching the factory at all.
A producing factory is not yet an approved supplier
Reuters identified a particularly important intermediate step: Vulcan Elements has begun producing magnets in North Carolina, but its customers had not yet approved them for use at the time of reporting. It also described MP Materials expanding magnet production in Texas under a Pentagon partnership. These examples show that industrial progress is not a binary choice between a project existing only on paper and complete supply independence. Construction, commissioning, stable production, customer qualification and recurring deliveries are separate milestones. The evidence needed to judge each stage differs. [1]
Qualification matters because a component must perform inside a specific product over its intended life. Magnetic characteristics, dimensions, thermal behaviour and consistency can all affect suitability. A substitute may require testing or a redesign rather than a simple supplier switch. For investors, nominal annual capacity therefore should not be treated as equivalent to immediately saleable production. The stronger questions concern qualified customers, usable output, rejection rates, delivery reliability and realised prices. An attractive facility announcement can coexist with a lengthy period of technical work and cash consumption before the business becomes a dependable commercial supplier.
Public support buys resilience, but does not remove execution risk
Government financing can address a coordination problem: a new processor needs buyers, while those buyers hesitate to commit before a reliable processor exists. Long-term purchasing arrangements and financial backing can support investment through that gap. But an equity stake, loan or procurement commitment is not the same instrument, and none guarantees the completion of every project. Reuters reports that a Korea Zinc-backed Tennessee refinery is not expected to open until 2030 and that several US mineral projects have later production targets. Those dates are plans, not completed output, and the refinery covers copper, zinc and other minerals rather than constituting a complete magnet supply chain. [1]
The commercial trade-off is that resilience may initially cost more than sourcing from an established producer with scale and accumulated expertise. A customer can rationally pay a premium for dependable alternatives, but that premium must support a workable cost base. Public backing may reduce financing risk while leaving commissioning, operating and demand risks intact. Shareholders also need to understand dilution, capital requirements and who bears losses if a project disappoints. Strategic importance can justify policy support without establishing that every associated security offers an attractive valuation or that government involvement guarantees private returns.
The same diplomatic headline affects producers and users differently
An extension of export-control waivers could ease immediate procurement pressure for manufacturers that depend on Chinese supplies. It might also reduce the urgency of some purchases from more expensive alternatives. Those channels need not affect all mineral companies similarly: an established qualified supplier, a developer still raising capital and a processor purchasing feedstock have different exposures. The price of a mined material also need not move with the margin earned on a finished magnet. Treating the sector as one uniform trade overlooks where each company sits in the chain and what its contracts actually protect.
For downstream manufacturers, reliable access can support output and cash conversion even without a dramatic fall in component prices. For a new non-Chinese supplier, the relevant question is whether customer commitments persist when immediate shortages ease. A durable contract can preserve the diversification case; reliance on temporary scarcity premiums makes it more vulnerable. Currency movements, energy costs and financing conditions add further differences. No particular share-price reaction is asserted here. The useful investment comparison is between contractual demand, operating readiness and the valuation already assigned to those prospects, not between companies sharing a fashionable strategic label.
Recycling and substitution help, but operate on different timetables
The IEA projects global demand for magnet rare earths rising by roughly one-third by 2030 under current policy settings. That is a scenario-dependent forecast, not consumption already realised. It also identifies magnet production as the principal diversification bottleneck, with investment needed beyond mining. Demand growth makes the challenge dynamic: alternative supply has to expand while the market it serves is also changing. Simply maintaining today's non-Chinese output would not maintain the same degree of resilience if the volume required by customers increases. [2]
Recycling manufacturing scrap can recover useful material sooner than waiting for long-lived equipment to reach end of life. Collecting used products requires logistics and processes capable of recovering suitable inputs. Substitution can reduce exposure in particular applications, but different motor or magnet designs involve performance, cost and engineering trade-offs. Neither approach should be dismissed, and neither should be assumed to replace every requirement immediately. The strongest resilience strategy combines better inventory planning, technically qualified alternatives and recoverable material flows. Its success is measured through dependable supply to users, rather than the number of initiatives announced.
What would turn a trade accommodation into lasting resilience?
A constructive near-term path would involve a documented agreement, workable licensing arrangements and consistent deliveries while alternative suppliers complete qualification. A less favourable path would preserve diplomatic language but leave authorisations slow or uncertain. A sharper disruption would constrain deliveries before replacement capacity could respond. These are conditional mechanisms, not probabilities assigned to the summit's outcome. A truce can buy valuable time, but its economic benefit depends on how that time is used: completing missing industrial stages matters more than repeating an ambition to become independent.
The practical watchlist is specific: the scope and duration of any signed export arrangements, actual shipment reliability, plant commissioning, customer approvals and contracted deliveries. Company reporting should distinguish nameplate capacity from saleable output and public financial commitments from cash received. Procurement teams should examine whether the alternative chain still depends on a concentrated processing step elsewhere. The central lesson before the talks is that bargaining power comes from the ability to operate without interruption. Mineral diplomacy can protect that ability temporarily; qualified, competitive production is what can make it durable.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- 1. Reuters, US minerals strategy ahead of the Trump-Xi talks (15 November 2026)
Full syndicated Reuters report by Jarrett Renshaw and Ernest Scheyder, checked directly. Negotiating possibilities, project schedules and customer qualification are retained as reported, not presented as completed decisions or output.
- 2. International Energy Agency, Rare Earth Elements: executive summary (revised May 2026 report)
Official text checked through the web reading service; direct automated access was blocked. Shares of 60%, 91% and 94% refer to 2024 magnet-rare-earth production stages, not current capacity. Demand growth is a forecast under existing policy settings; 2025 disruptions are historical.