Different bottlenecks, different economic shocks
Suez connects the Mediterranean with the Red Sea and shortens many journeys between Europe and Asia. Bab el-Mandeb lies at the southern entrance to the Red Sea. These are connected parts of a route, not interchangeable names for the same location. Panama links the Atlantic and Pacific, while the Strait of Hormuz is especially important for energy shipments from the Gulf. An incident in one passage therefore affects a different mix of cargoes and destinations from an incident in another. Treating all maritime headlines as an identical oil-price signal loses that distinction.
The disruptions examined by UNCTAD in February 2024 had different origins. Attacks on shipping in the Red Sea created security and insurance concerns; drought constrained operations at the Panama Canal; war complicated Black Sea trade. Their interaction mattered because diversion is not costless. A vessel rerouted around southern Africa may avoid one danger while spending longer at sea. A canal affected by insufficient water cannot necessarily solve its problem by adding staff or reducing fees. The physical constraint determines which alternatives are realistic.
How longer voyages turn into tighter capacity
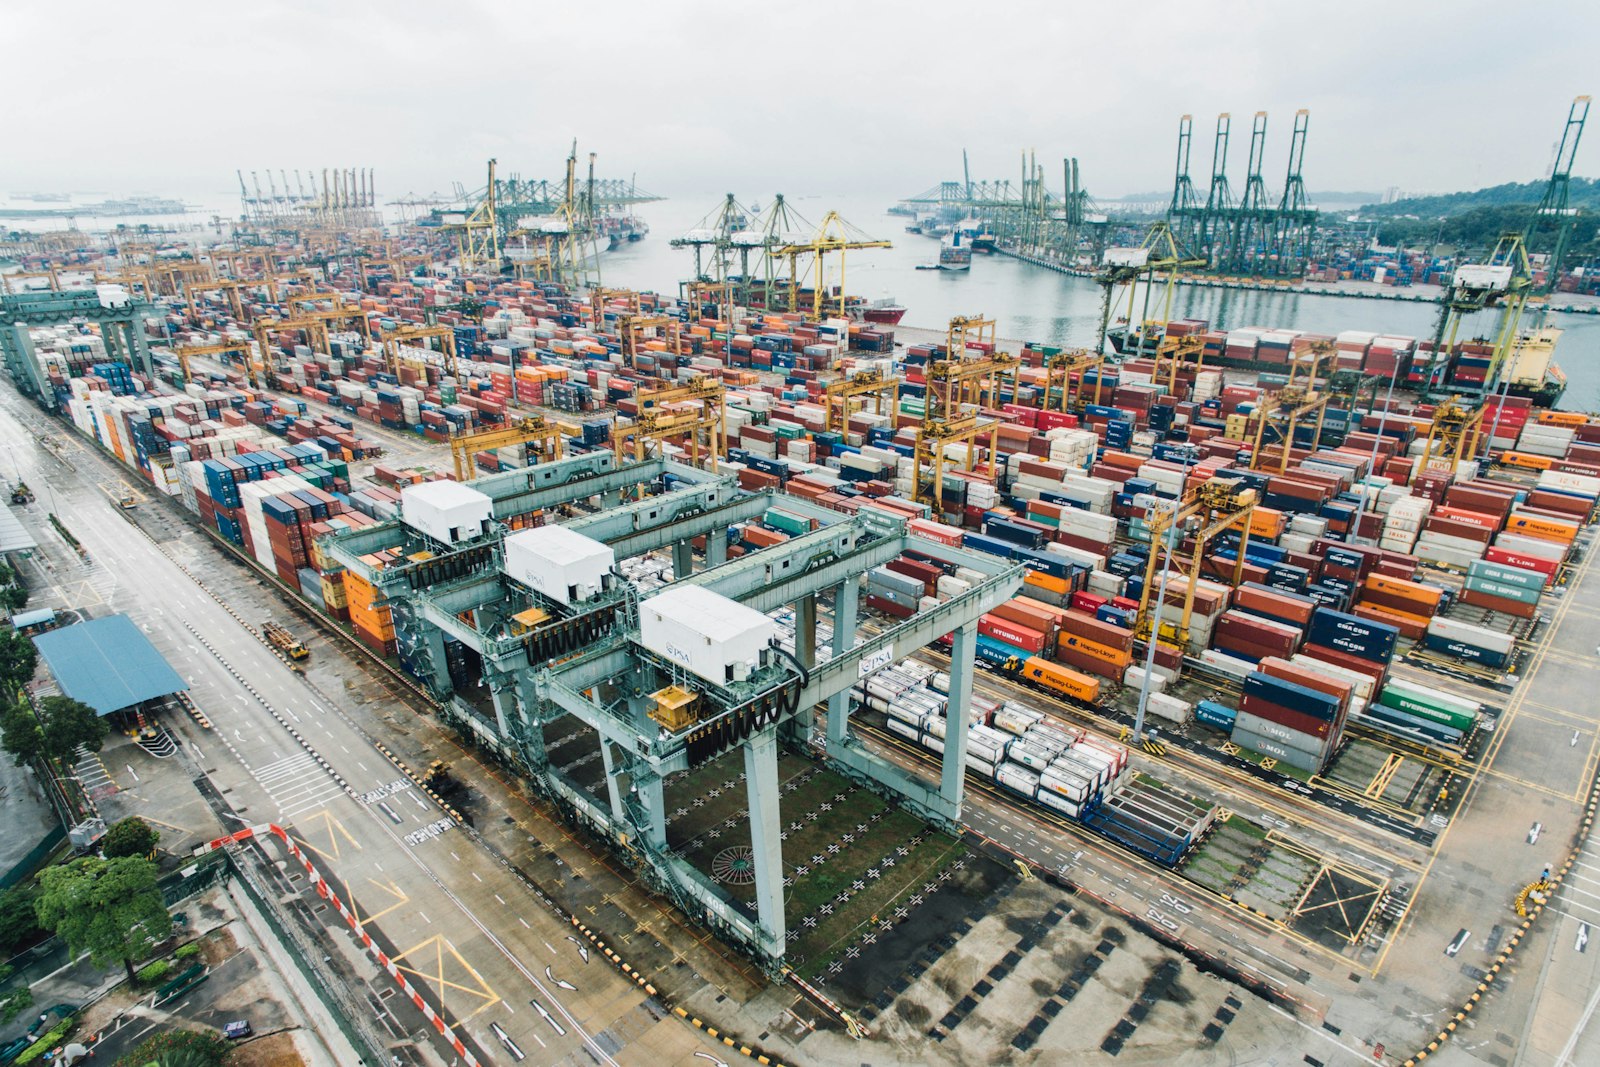
Shipping capacity is a service delivered over time, not just the number of ships in existence. If a vessel needs more days for each round trip, it can complete fewer voyages within the same period. Maintaining the original delivery schedule then requires additional ships or a reduction in service elsewhere. Longer routes may also consume more fuel and make container repositioning more difficult. A company with no supplier in the affected region can still experience delays if the equipment or vessel it needs has been displaced within the wider network.
That mechanism helps explain why spot freight rates can react sharply before a retailer experiences a visible shortage. But a spot quotation is not the cost paid by every customer. Large importers may have contracts negotiated earlier; smaller businesses may be more exposed to current rates. Some carriers operate in container shipping, others in dry bulk or tankers, with different fleets and demand. A rise in one container-rate index cannot establish that the entire shipping industry is earning the same windfall. Contract structure, utilisation and operating expenses all matter.
The route from freight to inflation is conditional
Higher freight costs can increase the delivered price of imported goods, but the pass-through is neither immediate nor one-for-one. Transport is only one part of a product’s final price. Businesses may absorb the increase in their margins, use inventories purchased at earlier prices, renegotiate with suppliers or raise selling prices only when contracts reset. Strong demand makes it easier to pass costs on; weak demand can force a company to accept lower profitability instead. Exchange rates, energy prices and wages can offset or amplify the same shipping shock.
Duration is therefore crucial. A short disruption may create a temporary scheduling problem; a persistent one can encourage additional inventories, supplier changes and repricing. Food and energy deserve particular care because they have different trade patterns, storage constraints and political sensitivities from manufactured goods. A headline about container diversions does not by itself establish a shortage of crude oil or wheat. To assess inflation risk, follow the relevant cargo, destination, contract and inventory rather than attaching one universal conclusion to the word “shipping”.
What markets may price, and what they cannot prove
The most directly exposed market observations are freight rates, insurance costs and the earnings expectations of carriers and import-dependent firms. Retailers, manufacturers and logistics operators can face different pressures even during the same episode. A carrier may benefit from higher prices while paying more for fuel and longer voyages. An importer may preserve sales but tie up more working capital in goods still at sea. The direction of the profit effect depends on the balance between pricing power and added cost, not simply the sector label.
Oil, currencies and government bonds are further along the chain of interpretation. An energy-route threat could raise concerns about supply, yet weaker expected growth could simultaneously depress demand. A currency may respond to import costs, risk aversion or interest-rate expectations. Bond yields could rise if inflation expectations increase, or fall if investors seek safety and anticipate weaker activity. When several markets move together, that is a useful observation, not proof that one shipping event caused all of them. Other economic releases and policy decisions may be moving prices at the same time.
Resilience has a price, and geography does not remove every risk
Governments and companies can reduce exposure by diversifying suppliers, holding more inventory or bringing selected production closer to customers. These changes may make an operation less dependent on one passage, but they are not free. Additional inventory uses capital and storage; duplicate suppliers require qualification and coordination; a new factory needs labour, energy and financing. A more resilient supply chain may be more expensive in normal conditions while reducing the damage of an exceptional disruption. That is an insurance-like trade-off, not necessarily evidence of inefficiency.
“Friend-shoring” also needs to be distinguished from a geographical shortcut. A supplier in a politically aligned country can still rely on the same shipping lane or on inputs from a less aligned economy. Conversely, a nearby supplier can be exposed to local weather, electricity or labour risks. Trade fragmentation can therefore change the location of vulnerability rather than eliminate it. Serious analysis follows the underlying inputs and transport routes instead of assuming that a change in the final supplier’s address has solved the entire problem.
A disciplined way to follow the next disruption
Start with verified route conditions: which passage is affected, what kinds of ships are changing course, and whether the restriction is legal, physical or security-related. Then look for evidence that the disruption is persistent: transit volumes, voyage times, carrier notices and relevant freight quotations. Only after that should the analysis move to the firms and countries that actually use the route. A company’s latest disclosures can be more useful than an attractive but loosely related sector index.
The next step is to separate observations from scenarios. An observed rise in transport costs is different from a forecast that consumer prices will rise. A delay reported by an importer is different from a national inflation outcome. Keep the dates aligned, compare with an appropriate baseline and state what would invalidate the interpretation, such as traffic normalising or weak demand limiting pass-through. Maritime chokepoints deserve attention precisely because their effects are interconnected. The strongest conclusion is not a dramatic universal prediction, but an explicit account of who is exposed, through which mechanism, and with what uncertainty.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- UNCTAD, Review of Maritime Transport 2024
Historical trade-volume context and maritime chokepoint analysis, published in 2024.
- UNCTAD, Navigating troubled waters
February 2024 assessment of Red Sea, Black Sea and Panama Canal disruptions.
- UNCTAD, Shipping disruptions and global trade
Dated February 2024 observations, not current transit readings.