A chip is the visible end of an invisible chain
Semiconductors are often described as a single product, as if the industry produced one interchangeable component. It does not. Memory, processors, sensors, power devices and analog chips serve different purposes and are made with different processes. A smartphone, a car, a data center and a medical device may each contain dozens of chip types. When a headline says that chips are scarce or abundant, the first question is always which chips, for which uses, and at which stage of production. Aggregate statements about the semiconductor market can hide very different conditions in its segments.
The Semiconductor Industry Association estimated global semiconductor sales at $627.6 billion in 2024, a record year driven partly by demand related to artificial intelligence and memory. That figure describes revenue, not the volume of chips or the profitability of every producer. It is a dated 2024 observation from an industry body, not a reading of market conditions in October 2026. This article uses it as structural context for understanding how the industry is organised, alongside OECD analysis of the chip supply chain.
Design, equipment, wafers and assembly are separate businesses
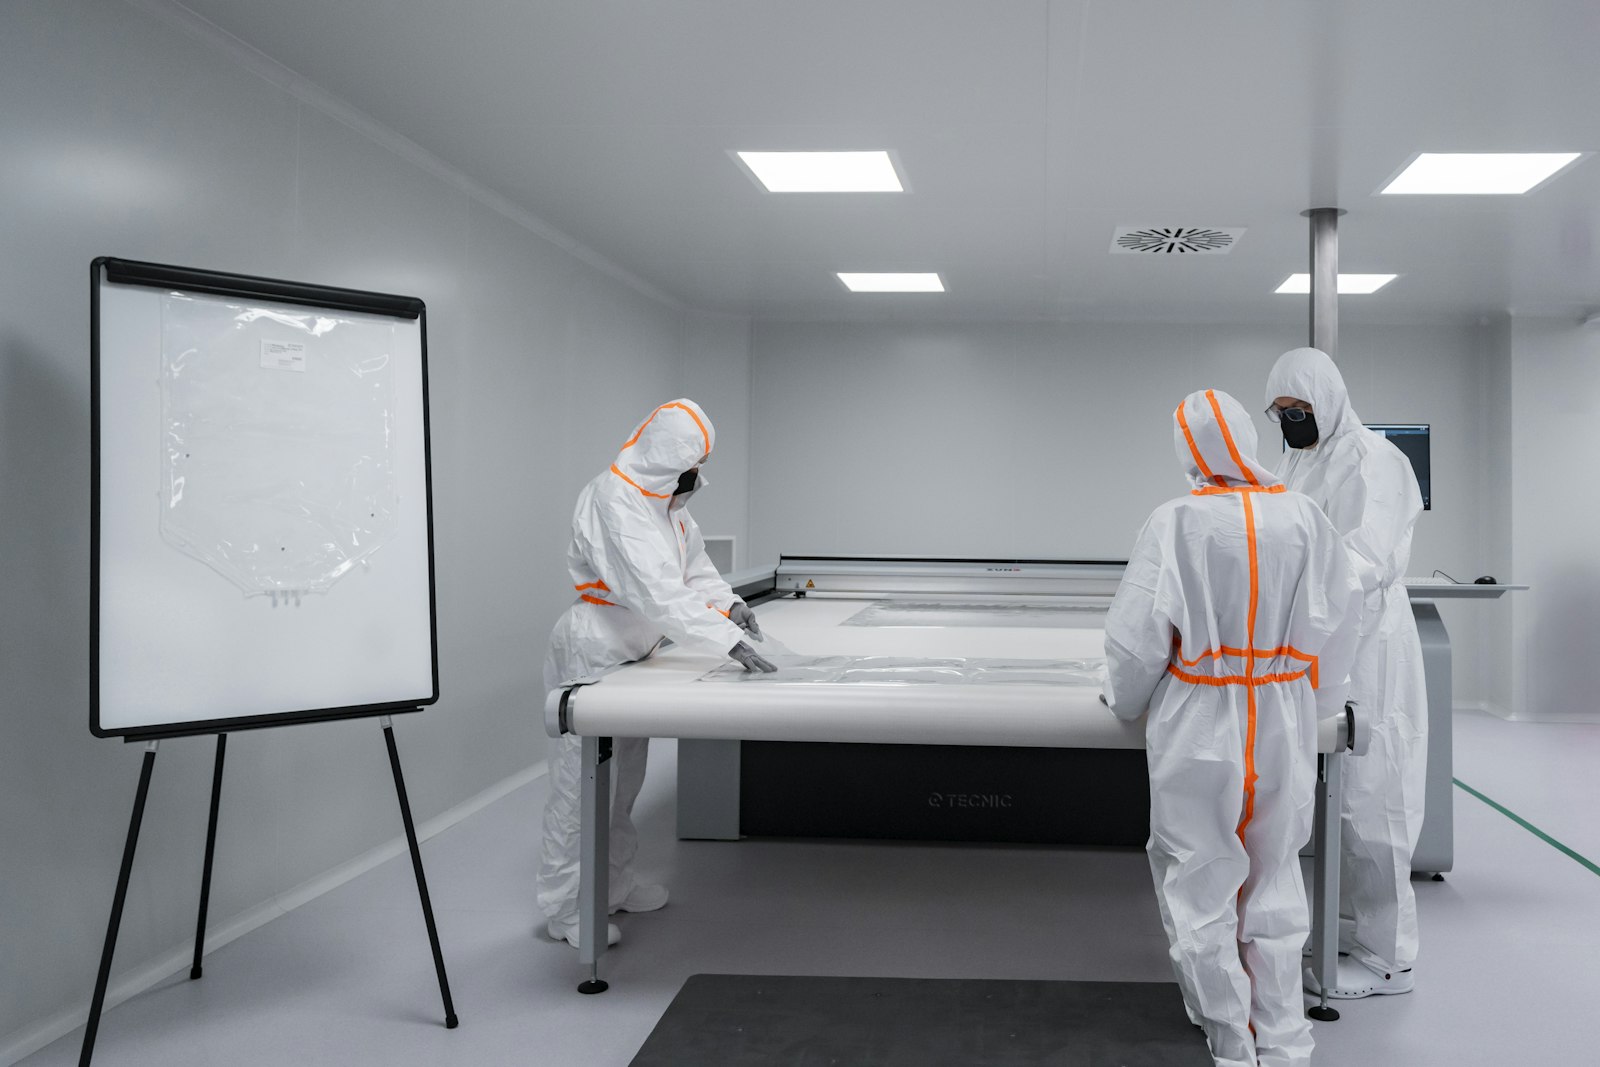
Producing a modern chip involves several distinct stages, each dominated by different firms and often different countries. Design requires specialised software and intellectual property. Manufacturing requires lithography and other equipment that only a handful of suppliers can produce at the frontier. Fabrication turns silicon wafers into circuits inside cleanrooms where particles smaller than a grain of dust can ruin production. Assembly, testing and packaging complete the product, frequently in yet another location. A company can be a leader in one stage and absent from the others.
This division of labour creates efficiency and vulnerability at the same time. Specialisation has lowered costs and accelerated innovation, but it also means that a disruption in one specialised input can constrain firms far downstream. The OECD’s work on semiconductor supply chains highlights precisely this interdependence: no economy currently performs every stage of frontier production alone. Analysing chip policy therefore requires mapping the specific stage under discussion rather than treating semiconductors as one national industry that a country either has or lacks.
Why building a fab is not like building a factory
A leading-edge fabrication plant is among the most capital-intensive industrial facilities ever built, with reported costs reaching tens of billions of dollars for a single advanced site. The building is only part of the expense: equipment, process development and the years required to reach reliable high-yield production matter as much. A fab that cannot produce a high share of working chips is an expensive shell, whatever its nominal capacity. Announced investment figures should therefore be read as intentions, not as available supply.
The workforce constraint is equally real. Advanced manufacturing requires engineers and technicians with experience that takes years to accumulate, and several governments and industry groups have warned of skills gaps in their dated assessments. Utilities matter too: fabs need extremely reliable electricity and large volumes of ultra-pure water. A subsidy can accelerate a project, but it cannot compress the time needed to qualify a process, train a workforce or connect infrastructure. Timelines in press releases and timelines in production statistics are different objects.
The industry is structurally cyclical
Semiconductor demand moves with investment in electronics, data centers, vehicles and industrial equipment, while supply responds with long lags. When demand rises, firms expand capacity, but new fabs arrive years later, sometimes just as demand cools. The result is a recurring pattern of tight markets followed by periods of excess capacity and falling prices, visible in the historical sales series published by industry associations. A strong year does not prove a permanent shortage; a weak quarter does not prove decline.
The cycle also differs by segment. Memory chips behave more like commodities, with prices that can swing sharply. Specialised analog or power devices may have steadier demand tied to vehicles and industry. Cutting-edge processors are shaped by a small number of customers and design wins. Comparing a memory producer with a designer of custom chips using one sector index mixes these dynamics. Serious analysis starts with the segment, its inventory position and its customer base before drawing any conclusion about the industry as a whole.
AI changes the demand picture without suspending the economics
Investment in artificial-intelligence computing has concentrated demand on particular products: advanced processors, high-bandwidth memory and the packaging technologies that connect them. This has redirected capital and engineering effort toward those segments, while other parts of the market, such as chips for cars or consumer devices, have at times faced very different conditions. One segment’s boom is not the industry’s boom. Reading a record revenue figure as evidence that every chipmaker is thriving confuses aggregation with distribution.
Concentrated demand also carries its own risk. When a small number of large customers drive orders, their spending decisions can move the outlook for an entire chain of suppliers. Expectations about future AI investment are embedded in current valuations and capacity plans, which means disappointment would propagate through the same channel as enthusiasm. This is a statement about exposure, not a prediction that investment will rise or fall. The analytical task is to identify which firms depend on which spending, and on what contractual terms.
Industrial policy is reshaping where chips are made
Governments in the United States, Europe, Japan, South Korea, India and elsewhere have committed large subsidies to attract or retain semiconductor manufacturing. Their motivations combine economic security, employment and technological capability. Public money can change the location of a project, but the OECD and other observers note that subsidies do not remove the underlying economics: operating costs, supplier ecosystems and talent pools still determine whether a facility remains competitive once built. A fab located by policy still has to be run as a business.
Export controls add a second layer. Restrictions on advanced chips and manufacturing equipment aim to limit particular capabilities, and their effects depend on precise legal scope, licensing, enforcement and the availability of alternatives. Controls can redirect trade flows and encourage domestic substitution in targeted countries as well as constrain it. Announcements should be read for what they legally cover rather than for the ambition of their press language, and their industrial effects should be tracked through shipments, licenses and capacity data, not inferred from the announcement alone.
How chip economics reach wider markets
The most direct market observations are the earnings, inventories and capital spending of chipmakers, equipment suppliers and their large customers. Semiconductor indices are heavily weighted toward a few firms, so an index move can reflect one company rather than the sector. Equipment suppliers often see orders before fabs produce chips, which makes their disclosures an early, though imperfect, indicator of capacity intentions. Inventory data can signal whether tightness is easing or building, but only when matched to the right segment.
The spillovers are wider than the sector. Data-center construction affects electricity demand, real estate and utilities in the regions concerned. Vehicle and industrial production depends on mature-node chips that attract fewer headlines than frontier processors. Currencies and bonds in chip-exporting economies can respond to the cycle. None of these links justifies attributing a broad market move to semiconductors alone: interest rates, macroeconomic data and unrelated news move the same prices. The discipline is to identify the transmission channel and then ask what else could explain the observation.
A framework for following the industry without hype
A practical sequence starts with the segment: memory, logic, analog, power or equipment. Then check the dated evidence, such as industry sales statistics, company inventories, capacity announcements with realistic timelines, and government program details. Distinguish a signed subsidy, a construction start and qualified production. Compare demand claims with the spending plans of the small group of customers that dominate advanced demand, and note what would invalidate the interpretation, such as cancelled orders, delayed fabs or inventory accumulation.
Finally, keep the structural picture separate from the news cycle. The industry’s interdependence, capital intensity and cyclicality are slow-moving facts; daily price moves are fast-moving and often ambiguous. Semiconductors matter to markets because computing has become a general-purpose input to almost every sector, and because the chain that produces it is concentrated, specialised and slow to reconfigure. That justifies careful attention, not a permanent narrative of either shortage or dominance. The strongest analysis names the stage, the evidence and the uncertainty, and leaves the slogans aside.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- Semiconductor Industry Association, 2025 Factbook
Industry sales statistics, including the $627.6 billion figure for 2024; dated industry data, not current readings.
- OECD, semiconductor supply chain analysis
Structural analysis of supply-chain interdependence and government support measures.
- SIA and BCG, Global semiconductor supply chain report (2024)
Dated assessment of manufacturing footprint and concentration; not live capacity data.