Why a quiet central bank became a global variable
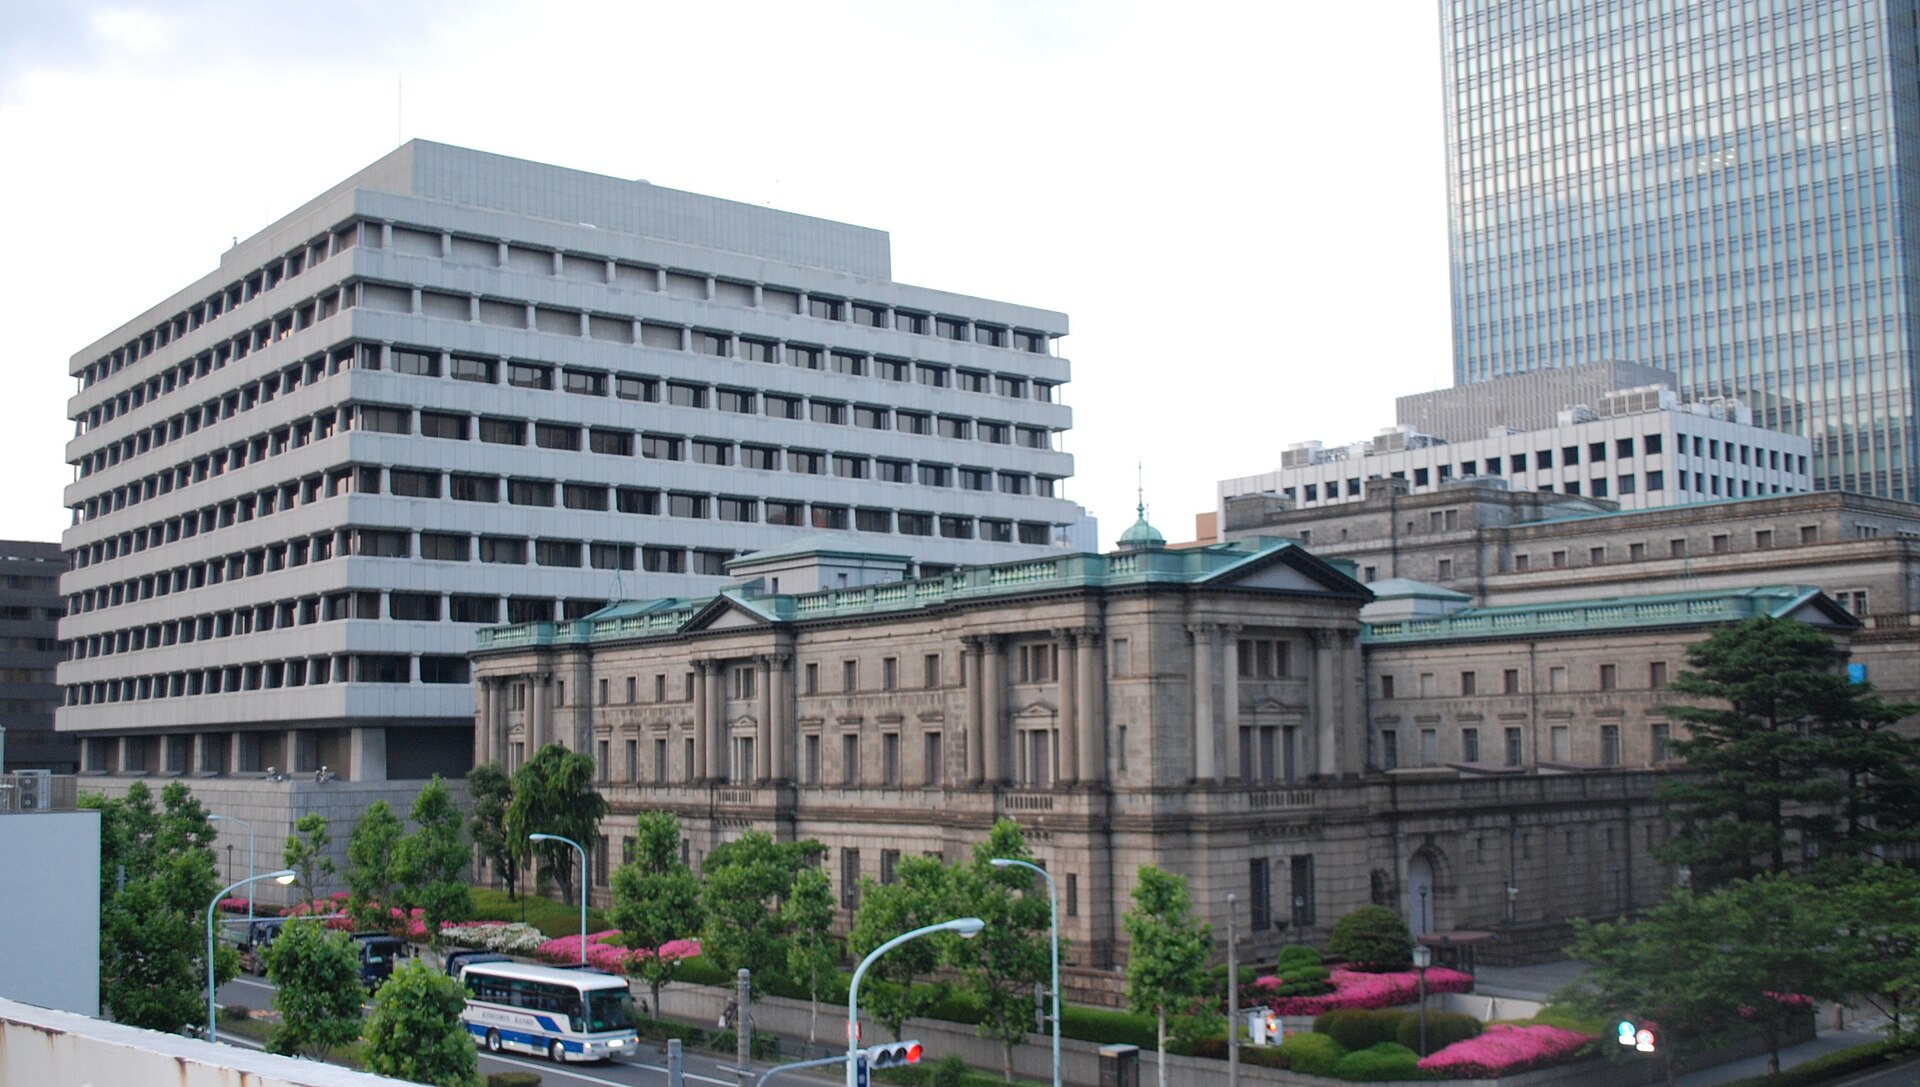
For most of the past quarter century, Japan was the one large economy where the price of money barely moved. Policy rates sat at or below zero, long-term yields were held down by the Bank of Japan, and the yen was the cheapest currency in the world to borrow. That stability was not only a domestic story. It turned Japan into a reservoir of low-cost funding and of patient savings that flowed into foreign bonds, foreign equities and foreign currencies. When the price of that reservoir starts to change, the effects travel far beyond Tokyo.
This article explains how that change has happened, what it revealed during the market turbulence of August 2024, and why Japanese money remains one of the variables that investors in the United States, Europe and emerging markets need to follow. It relies on the Bank of Japan’s own policy statements, on an analysis by the Bank for International Settlements, and on United States Treasury data on foreign holdings of American government debt. Where the evidence is uncertain, the article says so.
The central idea is simple. A country that lends a great deal to the rest of the world influences global prices through two channels: the cost at which others can borrow its currency, and the willingness of its own savers to keep money abroad. Both channels depend on the gap between Japanese interest rates and interest rates elsewhere. Narrow that gap, even gradually, and the incentives that have shaped global portfolios for years begin to shift.
March 2024: the end of negative rates
On 19 March 2024, the Policy Board of the Bank of Japan judged that a virtuous cycle between wages and prices had come in sight, and that its 2 percent price stability target could be achieved in a sustainable and stable manner. On that basis it concluded that its framework of Quantitative and Qualitative Monetary Easing with Yield Curve Control, together with the negative interest rate policy, had fulfilled their roles. From then on, the short-term interest rate would be its primary policy tool.
The decision ended the world’s last negative policy rate and the most ambitious attempt by a major central bank to fix the level of long-term government bond yields. It was carefully framed. The Bank said it anticipated that accommodative financial conditions would be maintained for the time being, and the increase itself was small. Markets therefore treated it less as a shock than as a change of regime: the direction of Japanese rates was now upward, even if the pace was expected to be slow.
A change of regime matters because many financial positions are built on assumptions about direction rather than level. An investor who borrows yen at almost zero to buy a higher-yielding asset does not need yen rates to stay at zero forever. The position depends on the yen not strengthening sharply, and on the funding cost not rising faster than the return on the asset bought. Once the central bank signals that rates have left the floor, both assumptions become less comfortable.
July 2024: higher rates and fewer bond purchases
On 31 July 2024, the Bank of Japan went further. By a 7 to 2 majority vote, it decided to encourage the uncollateralized overnight call rate to remain at around 0.25 percent. In the same meeting, and this time unanimously, it adopted a plan to reduce its monthly outright purchases of Japanese government bonds. The amount was to be cut by about 400 billion yen each calendar quarter in principle, so that purchases would be about 3 trillion yen a month in January to March 2026.
The two decisions belong together. Raising the policy rate changes the cost of short-term funding. Reducing bond purchases means the central bank, which had become by far the dominant buyer of Japanese government debt, gradually steps back and lets private investors set more of the price. That shift affects long-term yields in Japan, and through them the relative attractiveness of keeping Japanese savings at home rather than investing them abroad.
The split vote on the rate decision is also informative. It showed that the Board itself was not unanimous on the pace of tightening. For markets, that kind of disagreement widens the range of plausible outcomes, and a wider range of outcomes is exactly what leveraged positions dislike.
September 2026: the policy rate reaches 1.25 percent
Normalisation did not stop in 2024. On 18 September 2026, again by a 7 to 2 majority vote, the Policy Board decided to encourage the uncollateralized overnight call rate to remain at around 1.25 percent, with effect from 24 September 2026. The interest rate paid on financial institutions’ current account balances at the Bank was set at the same level, and the basic loan rate at 1.5 percent.
At 1.25 percent, Japanese short-term rates are still low by international standards, but they are no longer the near-zero anchor that the carry trade was built on. Each step reduces the cost advantage of borrowing yen, and the repeated 7 to 2 votes show that the Board continues to debate the pace. The next Monetary Policy Meeting is scheduled for 29 and 30 October 2026, together with a new Outlook Report on economic activity and prices.
August 2024: when the carry trade unwound
Days after the July decision, global markets went through a sharp but short episode of volatility. In its Bulletin on the event, the Bank for International Settlements described how the unwinding of leveraged trades in equity and currency markets amplified the initial reaction to a negative macroeconomic release in the United States. Markets then stabilised quickly and volatility receded. In other words, the trigger came from America, but the mechanism that turned a disappointing data point into a global sell-off ran partly through yen funding.
The BIS noted that currency carry trades were hit hard by deleveraging pressures, and that their overall size is difficult to measure. Combining estimates based on both on and off balance sheet activity, its authors arrived at a rough middle ballpark of about 40 trillion yen, or around 250 billion dollars, going into the event, and they warned that this figure is, if anything, biased down because of data gaps. That caveat is important. The true exposure was not visible in real time, and it is still not known precisely.
The authors described the episode as yet another example of volatility exacerbated by procyclical deleveraging and margin increases. When prices fall, lenders and clearing houses ask for more collateral; to raise it, investors sell other assets; those sales push prices lower again. An outright market dysfunction was averted, but the BIS argued that the structural features underpinning such episodes deserve continued attention from policymakers. The lesson for investors is not that the yen caused the turbulence, but that crowded positions financed in a cheap currency can turn an ordinary surprise into a disorderly one.
Japan’s weight in the American bond market
The second channel is less dramatic but probably more important over time: Japanese ownership of foreign assets, and in particular of United States government debt. According to the Treasury’s data on major foreign holders, Japan held 1,068.3 billion dollars of Treasury securities at the end of August 2026. It remains the largest foreign holder, ahead of the United Kingdom at 1,009.5 billion dollars. The same table shows Japanese holdings at 1,239.3 billion dollars in February 2026, which means a decline of roughly 170 billion dollars over six months.
These figures must be read with care. The Treasury data record holdings by country of the custodian, not always by the final owner, and changes reflect both purchases or sales and movements in market prices. A fall in holdings can mean that Japanese investors sold bonds, that the bonds they hold lost value as yields rose, or that the Japanese authorities used dollar reserves, for example to support the yen. The table alone does not say which explanation dominates, and this article does not claim to know.
What the data do establish is scale. A holder of more than a trillion dollars of American government debt does not need to sell aggressively to matter. If rising domestic yields make Japanese bonds a more attractive home for Japanese savings, even a slower pace of foreign buying can weigh on demand at the margin, at a time when the United States must refinance a large and growing stock of debt. The effect is likely to show up gradually in term premiums, rather than in a single day of market stress.
What it means for markets
Currencies are the most direct link. A narrower interest rate gap between Japan and the rest of the world reduces the reward for borrowing yen and investing elsewhere, which tends to support the yen over time. Yet the path is rarely smooth. Long periods of calm can rebuild carry positions, and sudden reversals can produce sharp yen rallies, as in August 2024. Investors in Japanese assets, and companies that export from Japan, are exposed to both phases.
For global bonds, the question is whether Japanese investors gradually repatriate savings. Domestic yields that are positive and rising compete with American and European government bonds once the cost of hedging the currency risk is taken into account. A shift of this kind would not be visible in one month of data, but it could contribute to higher long-term yields abroad, especially in markets where Japanese institutions have been large and steady buyers.
For equities, the transmission is indirect. Japanese stocks have benefited from a weak yen through the earnings of exporters; a stronger currency reduces that support. Elsewhere, the main risk is not Japanese selling as such but leverage: when funding conditions tighten suddenly, the most crowded trades, often in highly valued sectors, tend to be sold first. None of this establishes that a given market move was caused by Japanese policy. Co-movement in a stressed session can reflect many shared drivers at once.
What to watch next
First, the Bank of Japan’s statements after each policy meeting, starting with the meeting of 29 and 30 October 2026, and especially the balance of votes. A unanimous decision and a split decision send different signals about the future pace of normalisation. The schedule for bond purchases beyond the March 2026 target is equally important, because it determines how much of the Japanese bond market private investors must absorb.
Second, the monthly Treasury data on foreign holdings. A continued decline in Japanese holdings, if it persists while yields are stable, would suggest genuine selling or reduced reinvestment rather than valuation effects. Third, signs of rebuilt leverage: periods of very low currency volatility combined with a wide interest rate gap are the conditions in which carry positions grow again, often without being measured.
Finally, the American side of the equation. The BIS analysis is a reminder that the August 2024 episode began with a United States data release. Japanese normalisation changes the fragility of the system; it does not, on its own, decide when that fragility is tested. The prudent reading is therefore conditional: as long as Japanese rates rise slowly and predictably, adjustment can remain orderly, but surprises on either side of the Pacific can still be amplified by positions that nobody fully sees.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- Bank of Japan, Changes in the Monetary Policy Framework (19 March 2024)
Official statement ending the negative interest rate policy and Yield Curve Control.
- Bank of Japan, Change in the Guideline for Money Market Operations (31 July 2024)
Policy rate of around 0.25 percent (7 to 2 vote) and plan to reduce JGB purchases to about 3 trillion yen a month by January to March 2026.
- Bank of Japan, Change in the Guideline for Money Market Operations (18 September 2026)
Policy rate of around 1.25 percent from 24 September 2026, 7 to 2 vote.
- Bank of Japan, Monetary Policy Meetings schedule
Official calendar: next meeting on 29 and 30 October 2026, with an Outlook Report.
- BIS Bulletin No 90, The market turbulence and carry trade unwind of August 2024
Mechanism of the August 2024 episode and the rough 40 trillion yen (250 billion dollar) estimate of carry trades.
- US Treasury, Major Foreign Holders of Treasury Securities (TIC Table 5)
Monthly holdings by country; Japan 1,068.3 billion dollars in August 2026 and 1,239.3 billion in February 2026.