A steady policy rate, but a changing equity-market footprint
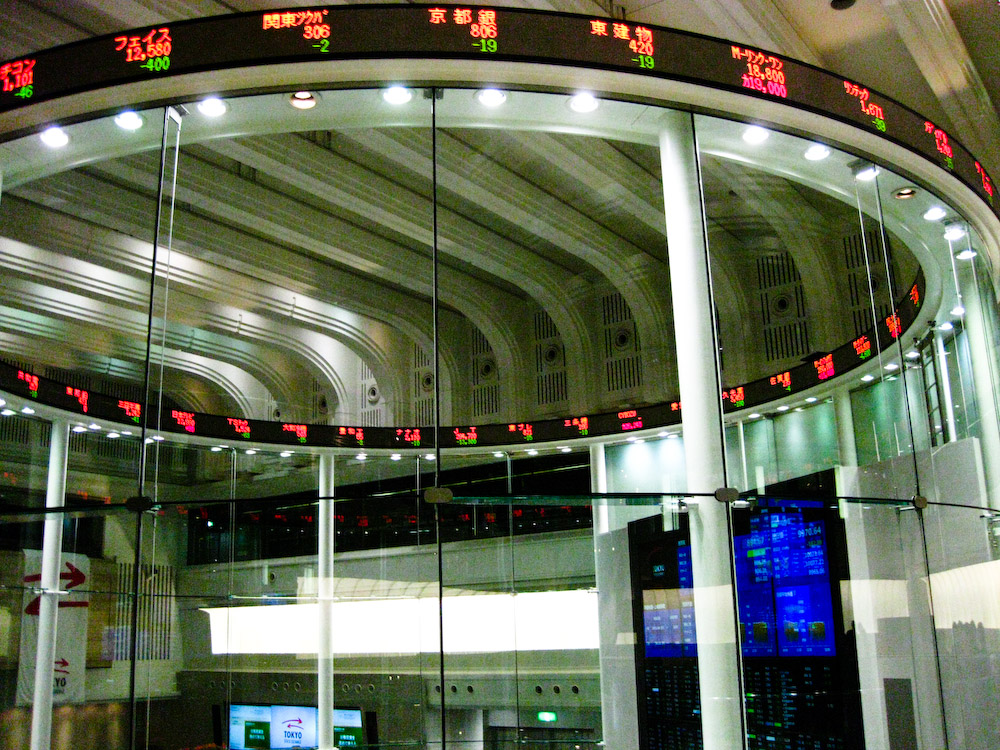
Japan’s central bank made two distinct decisions on 30 October. The Policy Board kept the uncollateralized overnight call-rate guideline at around 1.25%, by eight votes to one. Separately, it unanimously agreed to accelerate sales of its exchange-traded fund holdings from January 2027. The planned annual pace rises from about ¥330 billion to about ¥860 billion on a book-value basis. The immediate policy rate is unchanged; the future flow of central-bank equity sales is not. Treating the meeting simply as a rate hold misses that second adjustment. [1]
This is a different question from the familiar yen carry trade. It concerns the withdrawal of a public-sector owner from equity funds and the capacity of private investors to absorb the holdings over time. A gradual exit need not produce a disorderly market. But an owner that bought assets for monetary-policy purposes does not behave like an ordinary investor choosing shares for expected returns. Its departure changes the ownership environment, even when the volume released on any particular trading day is small. The useful analysis separates the announcement, the implementation date and the eventual effect on prices. [1][2]
¥860 billion is not the same as the value sold in the market
The distinction between book value and market value is essential. The Bank puts the new annual pace at about ¥860 billion on a book-value basis. Using the market-to-book ratio of ETFs it sold from January through September 2026, it converts that amount into approximately ¥2,460 billion at market value. These are two presentations of the same planned sales pace under that conversion, not separate programmes to add together. The market-value equivalent is also not a guaranteed amount of cash proceeds in every future year: valuations and the mix of holdings can change. [1][2]
The scale is calibrated against trading activity. The earlier programme represented about 0.05% of market trading value; the revised programme targets about 0.1%. The annual book-value pace therefore increases by more than the simple doubling of the turnover share. The Bank’s calculation uses Tokyo Stock Exchange Prime Market trading value and the market-to-book ratio for January through September. Changing activity and valuation enter the calibration. Comparing only ¥330 billion with ¥860 billion, without those definitions, makes the exit look simpler than it is. Neither measure tells readers the percentage of all Japanese equities that will be sold in a year. [1]
The exit is larger, not an immediate liquidation
The higher pace begins in January 2027, not on the day of the October announcement. The Bank says it started selling ETFs in January 2026 and has conducted those sales smoothly while avoiding a major market impact. It also says stock-market trading value has expanded. Those are the stated reasons for revising the pace. The revised framework allows temporary adjustments or suspension within the annual sales pace in response to financial-market conditions. J-REIT sales remain at about ¥5 billion annually on a book-value basis, so the equity-fund change should not be described as an identical acceleration across every risk asset held by the Bank. [1]
The reference presentation estimates that disposal would take about 43 years at the revised book-value pace, versus about 112 years under the previous pace. Those numbers divide the end-September ETF balance by the annual pace. They illustrate the long horizon; they are not binding completion dates. Future decisions, valuations and implementation choices can alter the trajectory. The presentation also calls for sales approximately proportionate to each ETF’s share in the holdings and spread over time. This is a managed disposal programme, not a decision to choose particular companies for immediate punishment or reward. [2]
Private demand, not the sale headline alone, determines absorption
A sale transfers ownership rather than destroying the underlying company’s earnings. Its price effect depends on the demand available at the prevailing valuation. Domestic institutions, households or foreign investors could absorb additional supply if expected returns remain attractive. Alternatively, weaker earnings expectations or more expensive financing could make buyers require a lower price. The programme adds a flow to that balance, but does not settle it. The 0.1% turnover calibration points to a deliberately small share of trading activity; turnover itself is not a promise that liquidity will remain equally deep during stress. [1][2]
ETF trading also should not be treated as an automatic one-for-one sale of every underlying stock at the same instant. Market intermediaries can hold inventory, hedge exposure or use creation and redemption mechanisms. Transmission depends on the fund, counterparties and trading conditions. This analysis does not identify a particular stock as a casualty of the programme or claim a measured change in liquidity after the announcement. Such conclusions would need actual execution evidence, spreads, volumes and fund-level information. The broader ownership shift is real; a precise immediate price effect has not been established here.
The rate vote leaves a separate source of uncertainty
The policy-rate decision was not unanimous. Takata Hajime proposed a guideline of around 1.5%, arguing that underlying CPI inflation had reached the price-stability target and that the Bank should step up the pace toward a neutral rate. The proposal was defeated. This records one member’s assessment, not a new rate or a unanimous finding about the appropriate speed of tightening. The eight-to-one vote and the unanimous ETF vote therefore describe different decisions. Conflating them would turn a managed balance-sheet adjustment into a policy-rate increase that did not happen. [1]
For equities, both decisions can matter through different channels. The policy-rate outlook affects financing and the discounting of future earnings; ETF disposal affects the flow and composition of ownership. A company with refinancing needs can be sensitive to the former even if ETF sales are readily absorbed. A highly valued equity market can face changing demand even if the policy rate stays unchanged for a period. These effects can reinforce or offset one another. No single vote establishes the terminal interest rate, the future exchange rate or the return that Japanese stocks will deliver.
The bond market supplies context, not proof of an announcement effect
Official Ministry of Finance observations provide a useful dated baseline. Its October series gives the ten-year government-bond yield as 3.092% on 1 October and 2.876% on 29 October. That is a decline of 21.6 basis points between those observations, despite the still-positive level of domestic interest rates. The two-year yield on 29 October was 1.901%. These observations precede the 30 October decision. They cannot demonstrate the market’s reaction to that decision, and they should not be passed off as live quotations on 31 October. [3]
The Ministry’s two-year auction on 29 October recorded a weighted-average accepted yield of 1.905%, with a nominal coupon of 1.9%, for an issue maturing on 1 November 2028. Auction yield, coupon and the daily yield-series observation are distinct measures, even when their values are close. Together they show the financing environment into which the equity-exit plan arrives. They do not isolate the contribution of inflation expectations, future monetary policy, fiscal supply or investor preferences. A lower ten-year yield during October does not by itself prove improved fiscal confidence or rule out future volatility. [3][4]
The international link runs through relative returns and risk appetite
Japanese investors compare domestic equities and bonds with foreign alternatives after accounting for currency risk, hedging costs and portfolio constraints. A changing domestic opportunity set can influence that allocation. But the Bank selling ETFs is not equivalent to Japanese institutions selling foreign bonds: they are different actors, holdings and transactions. The sources here do not demonstrate capital repatriation, a current yen move or a change in foreign Treasury ownership. International consequences remain conditional on how private portfolios respond to valuations, financing and the broader economy.
Foreign investors also matter on the receiving side. They may view a gradual public-sector exit as a more market-driven ownership structure, or demand greater compensation for uncertainty about supply. Corporate earnings and governance can outweigh either interpretation. A currency move then changes the translated return of an unhedged foreign holder, while affecting exporters and importers differently. This is why the programme cannot be reduced to a universal bullish or bearish call. The analytical chain runs from implementation to private demand, valuations and financing, with currency exposure added explicitly rather than assumed.
What would distinguish a smooth exit from a difficult one?
A smooth path would combine predictable execution with sufficient private demand, functioning ETF markets and no persistent deterioration in liquidity attributable to the programme. A more difficult path would feature weaker earnings expectations or a financing shock alongside constrained demand for the released holdings. In stressed conditions the adjustment or suspension provisions could become relevant, but their availability is not a guarantee that prices cannot fall. These are scenarios rather than assigned probabilities. The reference document’s long disposal horizon supports gradualism; it does not eliminate uncertainty about the intervening economic cycle. [1][2]
The monitoring priorities are concrete: actual sales and implementation updates after January, changes in the pace or valuation conversion, ETF liquidity, corporate earnings, domestic financing conditions and subsequent policy-rate decisions. Compare market observations before and after new information using consistent timestamps, while checking competing explanations. The October decision changes the planned speed of Japan’s exit from equity-fund ownership, not the policy rate and not today’s executed sales. Its importance lies in a slow redistribution of market exposure from the central bank to private balance sheets, whose willingness to hold that risk must ultimately be earned. [1][2][3][4]
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- [1] Bank of Japan, Statement on Monetary Policy (30 October 2026)
Policy guideline 1.25%, eight-to-one vote; dissent proposed 1.5%. ETF pace ¥330bn to ¥860bn annual book value, approximately ¥2,460bn market-value equivalent, effective January 2027. J-REIT pace unchanged.
- [2] Bank of Japan, ETF sales reference presentation (October 2026)
Turnover calibration 0.05% to 0.1%; approximate 112/43-year arithmetic horizons, not promised dates. Proportionate holdings disposal, spread timing and temporary adjustment or suspension provisions.
- [3] Ministry of Finance, daily JGB yield series
October snapshot checked 31 October: 10Y 3.092% on 1 October and 2.876% on 29 October, down 21.6 basis points. 2Y 1.901% on 29 October. The rolling file may later change; these are dated pre-decision observations.
- [4] Ministry of Finance, two-year JGB auction (29 October 2026)
Weighted-average accepted yield 1.905%, coupon 1.9%, maturity 1 November 2028. Not a post-announcement reaction or live quote.