Two October forecasts, one uneven global economy
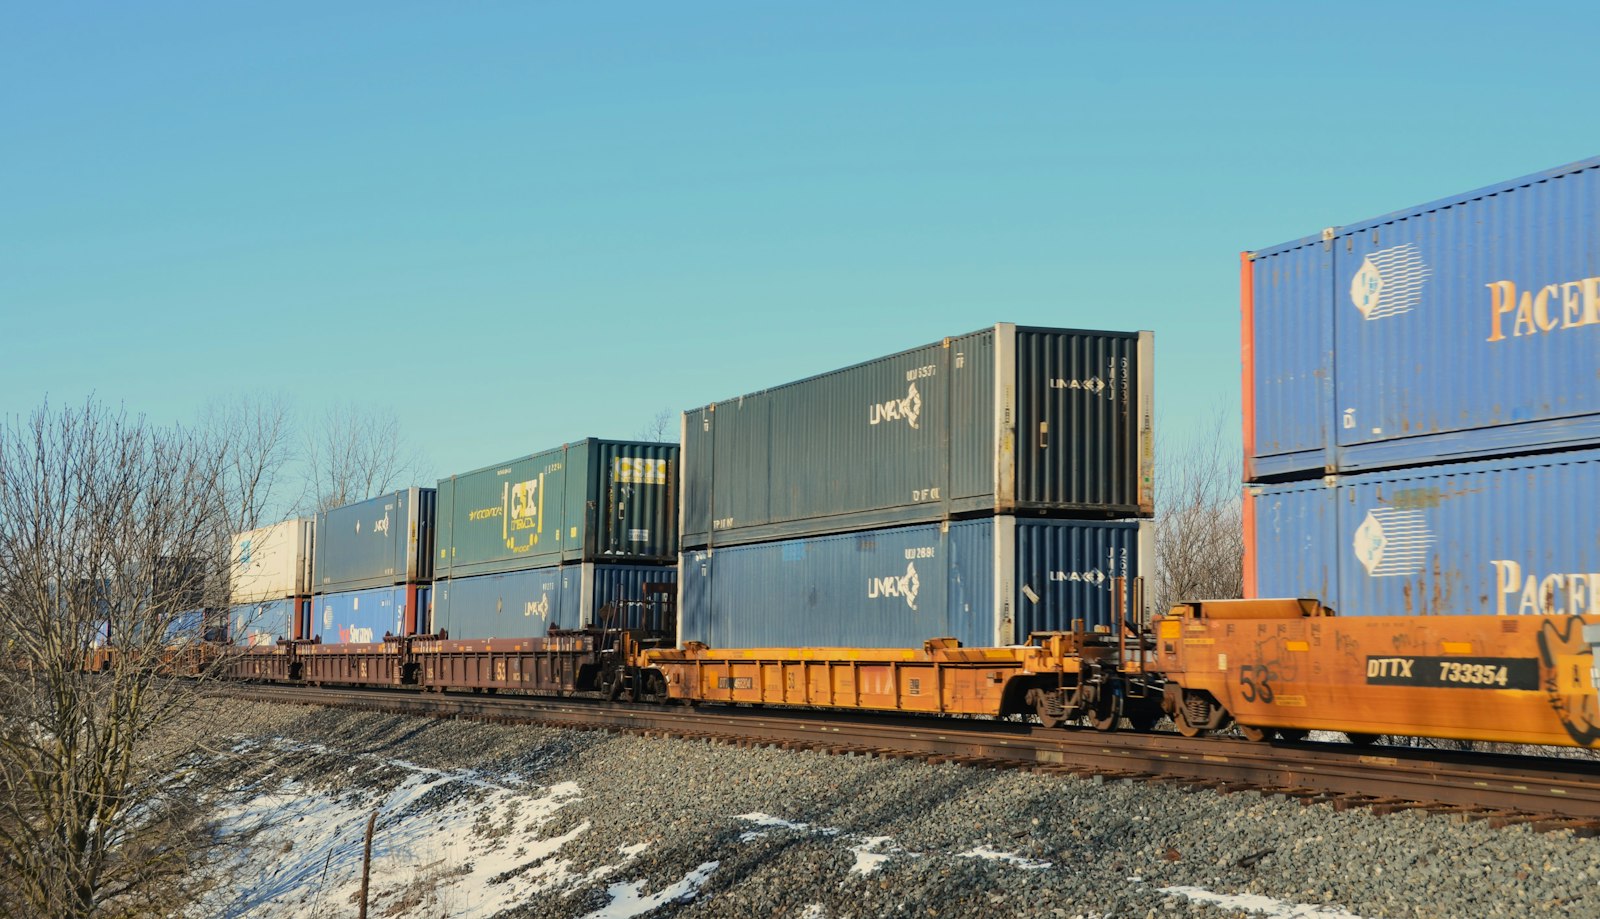
October’s official forecasts offer a more complicated picture than either a global boom or a universal retreat from trade. On 8 October 2026, the World Trade Organization raised its forecast for merchandise trade-volume growth this year to 3.9%, from 1.9% in March. It expects 4.1% growth in 2027. Meanwhile, the International Monetary Fund’s October World Economic Outlook projects global economic growth of 3.1% in 2026 and 3.4% in 2027. These are forecasts, not completed-year measurements, and the IMF specifies that its statistical information runs through 1 October. This article uses those dated publications, not an assumed live reading of the world economy.
There is no contradiction in goods trade growing faster than world output. Trade measures goods crossing borders, while economic output measures the value added within economies, including domestic services. Imported components can move through several countries before a finished product reaches its buyer. An investment boom concentrated in internationally traded equipment can therefore support merchandise trade without producing equally strong growth in household consumption or local services. The important question is not which headline is correct. It is which activities are expanding, who captures their income, and whether the expansion rests on durable demand or spending that can reverse.
Why goods trade proved more resilient than expected
The WTO attributes its upward revision to supply chains adapting to disruptions in energy and fertilizer markets, together with strong investment in artificial-intelligence-related infrastructure that supported trade in AI-enabling goods. Those are different mechanisms. Adaptation keeps transactions possible despite a shock: firms change suppliers, routes or inventories. Technology investment creates demand for equipment and components. Neither establishes that disruption has become harmless. A company may deliver the same volume while paying more for transport, working capital or substitute inputs. Resilience in quantities can coexist with pressure on profitability.
The revised forecast is also not evidence that trade barriers have disappeared. Companies can maintain shipments through expensive adjustments, and internationally integrated production can offer alternatives that a purely domestic system lacks. Yet the flexibility is uneven: a large multinational may finance extra inventory and qualify a replacement supplier more easily than a small importer. For market analysis, that distinction turns attention from aggregate tonnage to pricing power, sourcing flexibility and balance-sheet capacity. The WTO’s explanation supports an account of adaptation and concentrated investment, not a claim that every exporter has entered a new expansion cycle.
Services tell a less comfortable story
The same WTO update cuts its 2026 forecast for commercial services trade-volume growth to 3.3%, from 4.8% in March, while projecting 6.4% growth in 2027. It links the weaker near-term outlook to the Middle East conflict’s effects on transport and international travel. The upward revision in goods and downward revision in services should therefore be read together. They describe a change in the composition of cross-border activity, not a single improvement spreading across all businesses. The forecast rebound next year remains conditional, rather than a guaranteed recovery in bookings or receipts.
This divergence matters because services exporters have different economic exposures from equipment manufacturers. A supplier of computing infrastructure can benefit from capital expenditure while an airline or tourism business faces higher operating costs, disrupted itineraries or reduced demand. Even within transport, moving essential goods is not equivalent to moving discretionary travellers. Some flows continue because buyers have few alternatives; others can be cancelled or postponed. Investors should consequently avoid using a merchandise-trade upgrade as shorthand for the outlook of every internationally exposed company. A useful comparison separates order books, passenger demand, input costs and the timing at which each business recognises revenue.
Growth resilience does not remove the inflation constraint
The IMF’s October outlook projects global headline inflation of 4.7% in 2026, easing to 4.1% in 2027. These global figures conceal national differences and do not predict the policy decision of any particular central bank. The IMF identifies energy-importing economies outside the technology value chain as facing the most difficult outlook. That combination explains why growth can persist without delivering a comfortable policy environment: an economy may pay more for imported energy while capturing relatively little of the investment supporting global equipment trade.
An adverse supply shock differs from a simple collapse in demand. More expensive imported inputs can lift consumer prices while reducing real purchasing power and corporate margins. Cutting interest rates may support demand but cannot manufacture fuel or immediately repair a disrupted supply chain. Keeping policy restrictive can help contain inflation expectations but increases financing pressure on households and companies. The outcome depends on the duration of the shock, wage and price-setting behaviour, fiscal responses and the credibility of monetary policy. A trade-volume forecast alone cannot settle these trade-offs, and the global inflation projection should not be mistaken for a forecast of local interest rates.
Equities: follow value capture, not just shipment growth
For equities, the transmission from stronger goods trade to shareholder returns has several stages. More orders must become sales; sales must generate margins after labour, energy, freight and financing costs; profits must then justify the valuation investors already pay. A supplier can participate in a fast-growing investment cycle yet earn little if customers demand lower prices or competition forces heavy capital spending. Conversely, a company with modest volume growth may protect earnings through service revenue, specialised products or contractual pricing. These are analytical possibilities, not claims about a particular listed company’s October results.
The IMF also identifies a reassessment of AI expectations as a downside risk, while noting stronger investment and productivity gains as potential upside forces. The distinction between equipment demand today and productivity tomorrow is essential. Building infrastructure creates orders before the eventual users prove the commercial return on their expenditure. If expected returns disappoint, future orders or valuations can adjust even while current shipments remain strong. The disciplined market question is therefore whether capacity utilisation, customer economics and cash generation corroborate the investment story. Rising trade volumes establish activity; they do not establish that the price of an equity already reflects that activity conservatively.
Bonds and currencies: a supply shock can change the usual relationships
Government bonds respond to expected inflation, future policy rates and compensation for holding long-dated risk. Stronger growth may reduce expectations of rate cuts; persistent input-price pressure may do the same even when growth is weak. Conversely, a demand slowdown with easing inflation can support bond prices. The IMF’s April 2026 Global Financial Stability Report provides relevant background: it warns that more frequent supply shocks have weakened the equity–bond hedging relationship and increased the risk of simultaneous selloffs. That is a dated risk assessment, not a statement that such a selloff is occurring on 24 October.
Exchange rates introduce another layer. An energy importer may need more foreign currency to pay for the same physical volume of fuel, while an exporter receiving additional technology orders may see a different external-income effect. But currencies also respond to interest-rate expectations, capital flows and investor positioning; trade balances are not a complete exchange-rate model. A weaker currency can raise local import costs and worsen inflation, yet may also help some exporters whose expenses are primarily domestic. The net effect depends on invoicing currency, imported content, hedging and foreign-currency debt. Simply labelling a country an exporter or importer is too coarse to infer its currency’s next move.
When an economic divergence becomes a financing problem
The April Global Financial Stability Report highlights amplification channels that remain useful for interpreting the October outlook. These include rollover risk where governments rely on short-term borrowing, leverage among nonbank financial institutions, and sensitivity of emerging-market portfolio flows to global risk sentiment. They explain why a moderate change in economic expectations can have a larger financial effect. A borrower facing refinancing soon is more exposed to tighter conditions than one with long-term fixed-rate funding. An investor using leverage may have to reduce positions when collateral requirements rise, irrespective of the long-term economic argument.
This does not mean a crisis follows mechanically from weaker services trade or higher inflation. It means resilience must be assessed alongside the ability to finance it. Companies adapting their supply chains can require additional inventory and cash before receiving customer payments. Countries absorbing expensive imports may face pressure on external financing. The same shock can remain manageable for an economy with credible institutions and substantial buffers while becoming more disruptive elsewhere. The useful signals are funding costs, maturity schedules, liquidity and external financing needs, rather than an assumption that all internationally integrated economies share the same vulnerability.
What would strengthen, or weaken, the resilience thesis?
A constructive scenario would combine continued equipment investment with broader participation in growth, easing energy pressure and improving services activity. Its evidence would be realised trade data, stronger final demand and inflation releases consistent with stabilising costs, not simply another optimistic forecast. A less favourable scenario would see equipment investment concentrated in a narrow set of suppliers while energy costs and financing conditions squeeze other sectors. A more severe reversal could involve renewed trade restrictions, conflict escalation or a reassessment of expected technology returns. These scenarios describe conditional mechanisms; no probability or asset-price target is assigned because the cited reports do not justify one.
The next revisions should be read for their composition as well as their headline. Do actual goods volumes confirm the upgraded outlook? Do transport and travel recover? Are orders translating into operating cash flow? Are inflation expectations and borrowing costs becoming less restrictive? The WTO and IMF publications provide a starting framework, not a substitute for company disclosures or current market observations. Their shared lesson is that an integrated economy can adapt without distributing the benefits evenly. In October 2026, resilience is a defensible description of parts of world trade. Prosperity across countries, households and portfolios is a much broader claim, and requires much broader evidence.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- WTO, October trade forecast announcement (8 October 2026)
Merchandise trade-volume forecasts: 3.9% for 2026, revised from 1.9%, and 4.1% for 2027. Services: 3.3% for 2026, revised from 4.8%, and 6.4% for 2027. Describes supply-chain adaptation and AI-enabling goods.
- WTO, Global Trade Outlook and Statistics (October 2026)
Full October outlook underlying the goods/services comparison. Forecasts concern trade volumes, not equity returns or company earnings.
- IMF, World Economic Outlook (October 2026)
Global growth projections of 3.1% in 2026 and 3.4% in 2027; headline inflation of 4.7% and 4.1%. Statistical cutoff: 1 October 2026. Risks include conflict, AI expectations, renewed trade tensions and fiscal vulnerabilities.
- IMF, Global Financial Stability Report (April 2026)
Dated background on supply shocks, the equity–bond relationship, refinancing, leverage and emerging-market capital flows. Not presented as a live October market reading.