The strategic resource is a supply chain
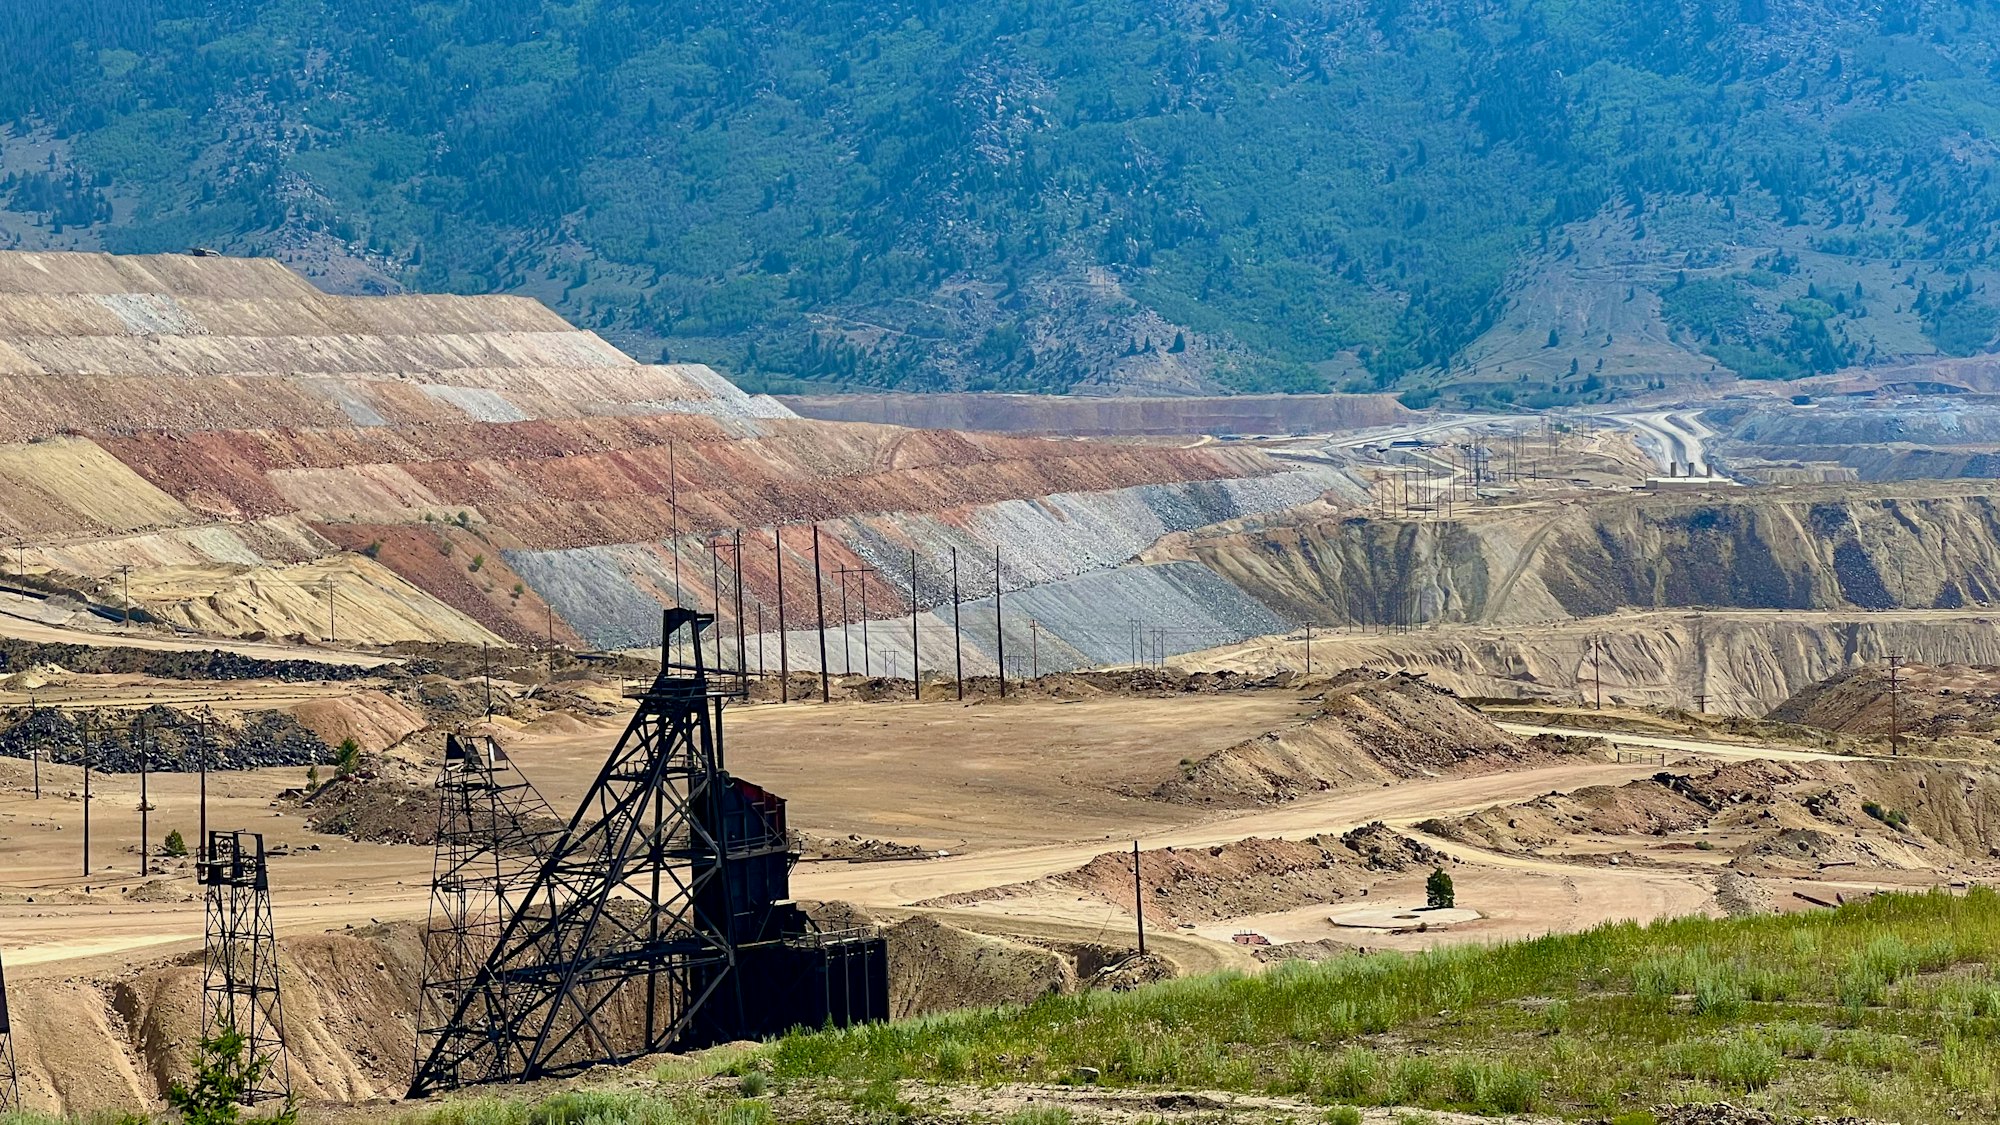
A deposit of copper, lithium or rare earth elements attracts attention because it appears to offer a tangible answer to an economic need. Yet geological availability is not the same as a dependable supply of usable material. Resources must be surveyed, permitted, financed, extracted and processed to the specifications manufacturers require. Each stage can take time and rely on skills, equipment or infrastructure located elsewhere. A country with extensive deposits may still depend on imported technology or foreign processing. Strategic influence therefore belongs to a chain of capabilities, not simply to the owner of a patch of ground.
The word critical also needs care. Materials become critical in relation to particular technologies, supply risks and policy priorities; they are not interchangeable commodities. Copper is important for electrical equipment and networks, while lithium is associated with many battery chemistries. Rare earth elements have specialised applications, including certain high-performance magnets. Some materials have diversified uses beyond the energy transition. This article uses the IEA’s 2024 and 2025 mineral outlooks as dated structural references. It does not present their projections as observations of current output or assume that every listed material faces the same shortage.
Why processing can matter more than extraction
Raw output must often pass through refining and further conversion before it becomes suitable for industrial use. That step can be geographically concentrated even when mining is spread across several countries. A buyer may diversify its ore suppliers without changing its dependence on a smaller set of processors. Capacity, technical expertise, energy prices and environmental regulation all influence where processing is economical. The resulting pattern can give one part of the chain significant leverage, especially when alternatives cannot quickly meet the required quality or scale.
The IEA’s outlooks distinguish mining from refining because concentration at those stages creates different risks. A disruption at a mine affects the material it produces; a restriction on a specialised processing product may affect manufacturers across several importing economies. Stockpiles and recycling can provide buffers, but not necessarily a complete substitute. For analysis, ask which form of the material is constrained, which customers need it and which alternative facilities are qualified. A generic statement that a country controls minerals can hide crucial differences between resources, production, processing and finished components.
Low prices do not prove that supply is secure
Commodity prices reflect the balance between supply and demand as well as inventories, financing and expectations. New capacity or softer demand can depress a price even while production remains concentrated. That creates an apparent contradiction: a material can be strategically important and commercially unattractive at the same time. Lower prices help buyers in the near term, but they can weaken the case for new projects in alternative locations. Security policy and market incentives may therefore pull in different directions rather than reinforcing each other automatically.
The reverse is also true. A sharp price rise can encourage investment and substitution, but a new mine or refinery is rarely available immediately. Existing producers may enjoy stronger revenue while paying higher operating costs or confronting political pressure. A price spike does not establish that every mining company is a beneficiary. The company’s particular product, extraction costs, hedges, royalties and debt matter. The analysis should distinguish the commodity price from the profitability of a specific asset and from the resilience of the wider supply chain.
The mismatch between industrial ambitions and project timelines
Manufacturers can announce new factories much faster than the upstream chain can reliably expand. A mining project may require lengthy studies, consultations, permits and construction. A refinery must demonstrate that it can produce consistent material at scale. Financing depends on expected prices and credible purchasers, while infrastructure and workforce availability affect execution. A target for future battery or grid production should therefore not be treated as a guarantee that all necessary inputs will arrive on schedule. The timing and dependencies of each project have to be aligned.
Long-term purchasing agreements can help by giving suppliers greater visibility over revenue. Government support can also reduce some commercial risks, but it does not eliminate engineering or operational problems. Subsidised capacity that is expensive or poorly executed can remain fragile. Equally, evaluating every project solely at a depressed spot price may undervalue the diversification it provides. The practical question is how much resilience a policy buys, at what cost and under which demand assumptions. That is a more useful framework than describing all industrial support as either wasteful or automatically strategic.
Technology can change the exposure
Demand is not a fixed destiny. Battery chemistry, equipment design, efficiency and recycling can change the amount of a material required for a given service. Substituting one input may reduce exposure to a particular mineral while increasing dependence on another. Alternatives also differ in performance, cost and suitability. A technology that works well for one application may not be acceptable for another. Investors should therefore treat mineral-demand scenarios as conditional pathways rather than extrapolating one technology’s current material intensity indefinitely.
Recycling is important, but its contribution depends on collecting suitable material and processing it economically. Rapid growth in a technology can mean that a large share of the installed stock is still in use rather than available as scrap. Quality requirements, recovery rates and collection systems influence how much secondary supply can actually replace primary production. Recycling does not make new extraction unnecessary overnight. Nor should it be ignored merely because it cannot solve every near-term problem. Its value depends on the material, the maturity of the product stock and the infrastructure available.
Trade restrictions reach beyond the commodity price
Export controls, tariffs and investment restrictions can change who is able to buy or build particular parts of a supply chain. Their impact depends on the legal scope, exemptions, enforcement and alternative supply. A control on a processed material is different from a ban on raw ore; a licensing requirement is different from a complete prohibition. Announcements must be read precisely before interpreting their consequences. Markets may respond to anticipated restrictions, but the actual industrial effect needs evidence about deliveries, inventories and qualified substitutes.
Diversification can involve new commercial partnerships, domestic processing or redesigning products. These responses require coordination and may alter costs for both producers and customers. Environmental and community concerns are part of execution, not details that can simply be excluded from an economic model. Projects depend on water, land access and social acceptance, and weak governance can create additional disruption risk. A credible supply-security strategy should therefore consider local impacts alongside geopolitical alignment. Moving production to a friendly jurisdiction does not automatically remove technical, ecological or operating vulnerabilities.
Reading the market without turning a theme into a trade
Begin with the most direct evidence: the price of the relevant material, inventories where reliable, utilisation of processing capacity and the disclosed position of exposed firms. Compare a miner with a refiner or a manufacturer rather than assuming they share the same incentives. A lower input price can support a customer’s margins while weakening a supplier’s cash flow. Currency movements and financing costs can further change project economics. Broad sector indices are useful context, but they can mask very different mineral mixes and stages of production.
Then separate structural exposure from the trigger for a daily price move. A company can be strategically relevant without every change in its share price reflecting geopolitics. Earnings, management decisions and general risk appetite may dominate on a particular day. A sound interpretation identifies the mechanism, the evidence and the competing explanations. It also states what would weaken the thesis, such as substitution, new capacity or lower demand. Critical minerals matter because industrial capabilities are unevenly distributed and slow to replicate. That insight supports disciplined analysis, not a guarantee of scarcity, high prices or investment returns.
Sources & scope
An explanatory analysis using the dated publications below. Historical figures are not live readings; scenarios are conditional, and market co-movement does not establish causation. Not investment advice.
- IEA, Global Critical Minerals Outlook 2024
Historical assessment of mining, refining, investment and energy-transition demand scenarios.
- IEA, Global Critical Minerals Outlook 2025
Dated assessment of market concentration, diversification and supply-chain risks; not live prices.